Greg Martel’s victims thought they were getting rich off Canada’s housing boom. Instead they lost everything. Will the notorious Ponzi schemer ever face justice?
Greg Martel’s victims thought they were getting rich off Canada’s housing boom. Instead they lost everything. Will the notorious Ponzi schemer ever face justice?
Based on facts either observed and verified firsthand by the reporter, or reported and verified from knowledgeable sources.
The $300 million-dollar con man
Greg Martel’s victims thought they were getting rich off Canada’s housing boom. Instead they lost everything. Will the notorious Ponzi schemer ever face justice?
In 2020, Barron and Nancy Harper sold their home in northeastern California and moved to Victoria, BC, to be closer to their son and daughter-in-law. The Harpers, both in their seventies, had dreamed about the move for years, and it felt like starting the next chapter of their golden years.
But Victoria is also one of Canada’s priciest cities, and the Harpers were comfortable, but not wealthy (he was a semi-retired tax accountant, she was a retired professor). After making a down payment on a house, they went looking for ways to shore up their retirement savings.
In 2020, their son told them about an exciting company he’d invested in called My Mortgage Auction Corporation, or MMAC. Its owner was Greg Martel, a gruff, forty-something mortgage broker whose business model, as he described it, was simple. He solicited investments from people like the Harpers, then loaned that money to property developers who needed cash to get new projects off the ground. The developers paid extraordinarily high interest rates—up to 1% weekly.
The Harpers had no reason to be skeptical. Their son was making steady money, and his wife, a realtor, recognized Martel’s credentials in the real estate business. It seemed like a chance to cash in on the property boom that was transforming the city, where new condos and apartments seemed to sprout from the soil like Douglas firs, and residents could count construction cranes rapidly proliferating across the skyline. So the couple pulled $15,000 out of their savings and invested it with Martel.
The best morning read in Victoria, bar none.
Stay connected to your city with the Capital Daily newsletter.
By filling out the form above, you agree to receive emails from Capital Daily. You can unsubscribe at any time.
Within weeks, the interest payments came in—and they were huge. Typical MMAC yields could be more than 15% on a loan of only three months.
Nancy Harper estimates, roughly, that the Harpers sank more than $400,000 into the company, accounting for about two-thirds of their net worth. They used their enlarged nest egg to go on vacations and provide cash gifts to their kids worth tens of thousands of dollars.
The money rolled in for more than two years. Then, in the winter of 2022, it abruptly stopped. Martel offered the Harpers a list of excuses. He blamed the Royal Bank of Canada, which handled his transactions. He said a glut of new investors had led to payment delays. He claimed the holdup stemmed from tax issues. But he promised their money would be there next week—then the next, then the next.
The Harpers were not alone. Across the city, frustrated MMAC investors were flooding Martel’s office with calls. Soon, they were finding each other online in group chats and on message boards. That’s when they realized no one was getting paid—that MMAC was a real estate empire constructed on quicksand.
As investors pieced together what happened, they discovered that there had been no developments and no loans. MMAC was, in fact, one of the biggest Ponzi schemes in Canadian history—one that had been convincing enough to compel more than 1,700 people to invest a combined $301 million. Most, though not all, were from Victoria and Vancouver Island. Some had put enormous sums, even their entire life savings, into the company.
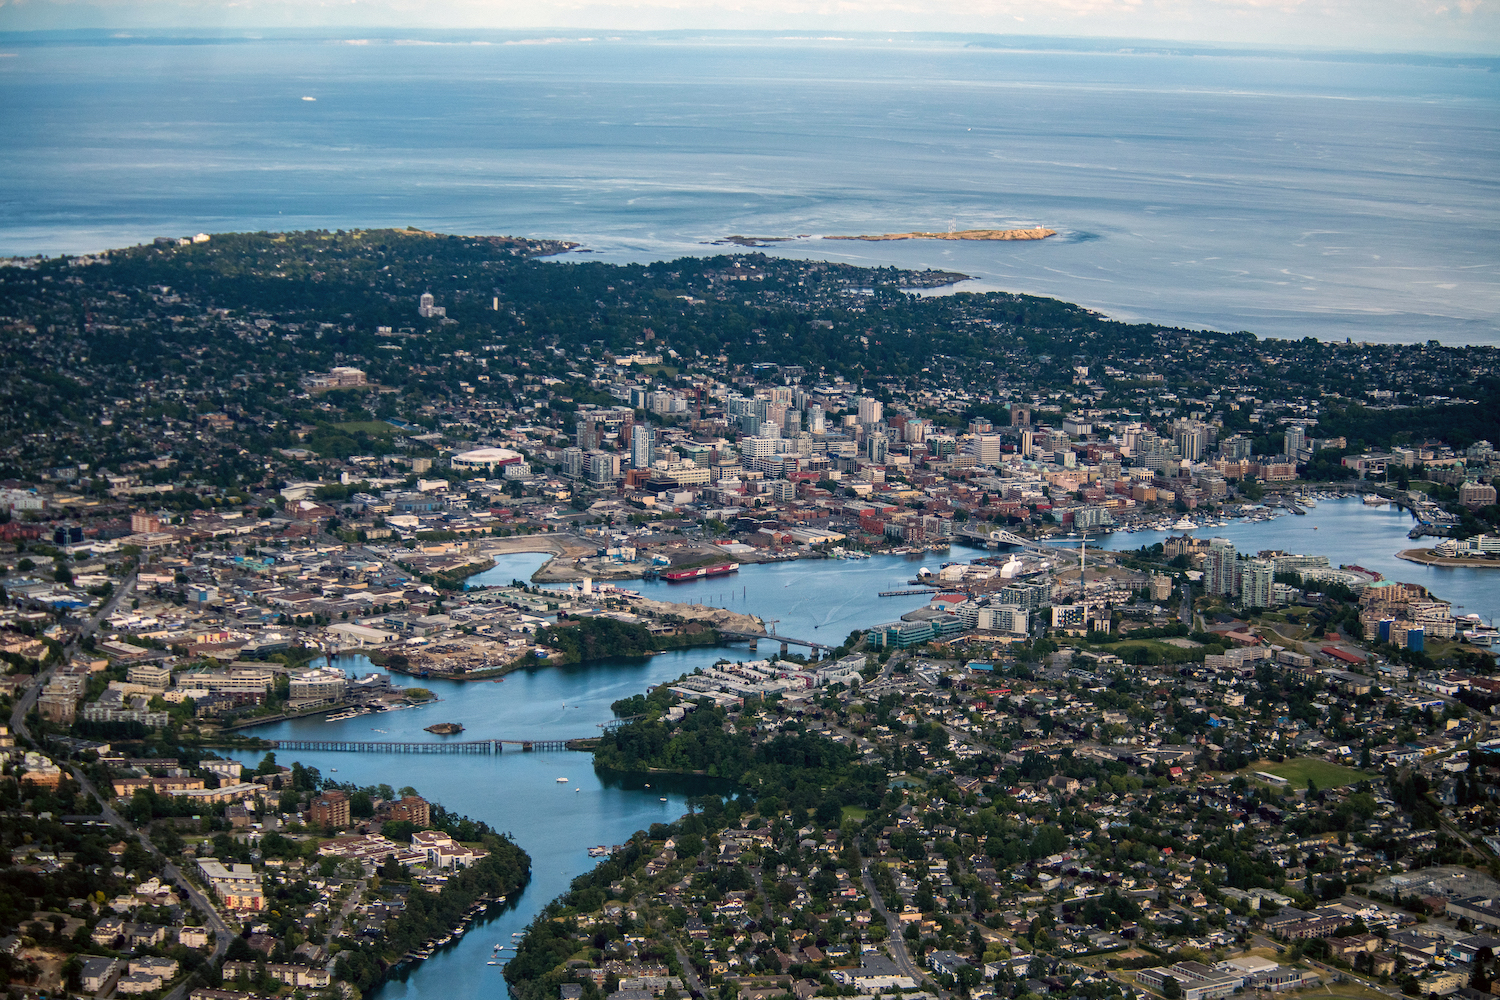
Most investors were from Victoria and Vancouver Island. Photo: James MacDonald / Capital Daily
I spoke with 15 of Martel’s victims for this story. Most were middle-class people: small-business owners, white-collar workers, single parents. Some, like the Harpers, were trying to boost their retirement savings. Others, ironically, hoped their MMAC returns could help them afford a down payment in Victoria’s red-hot real estate market. Many were embarrassed and asked me not to use their names. Their personal credentials—as realtors, bankers, financial advisers—exacerbated their shame. One victim told me that when she reported Martel to the Victoria Police Department, she was told the case was being handled out of Vancouver because several Victoria officers had also been defrauded by Martel. (When I asked the police department about this, they would neither confirm nor deny it.)
I’ve been reporting on white-collar crime for years and have spoken to many victims of fraud. I know that their humiliation often outweighs even their financial losses. Falling prey to fraud is often regarded as a failure of intellect, or of character. Many of Martel’s victims also blame themselves. But every one I spoke to also told me they feel betrayed by the institutions and safeguards they thought existed to protect them. Canada has plenty of tough rules and regulations intended to deter white-collar crime. In practice, however, we’re a country of stumbling enforcement, toothless penalties and endless opportunities for scammers to make off with their ill-gotten gains.
"Any savings that I had, I gave it all to Greg."
The BC Financial Services Authority, or BCFSA, which regulates mortgage brokers in the province, received complaints about Martel’s business as early as 2017. It investigated and found nothing untoward. Over a period of five years, RBC processed tens of thousands of transactions related to MMAC—yet at no point did it flag anything, at least publicly, like high-volume deposits or unusual account activity inconsistent with MMAC’s stated business. Some of Martel’s victims are now suing the bank, arguing it should have spotted unusual account activity earlier.
Many victims told me that their faith in these institutions has been destroyed. Even worse is that Martel has fled the country. He may never face justice on Canadian soil.
Building Greg Martel
Greg Martel was always a striver. Born in Quebec in 1976, he spent his teen years in Brampton, Ontario, and first visited Victoria in the early ’90s. He moved west in the early 2000s and, after a stint working with Scotiabank, he registered as a mortgage broker in 2006.
He quickly made a name for himself. Zamian Parsons is a Victoria realtor who was once friends with him. “He didn’t want to be the number-one mortgage broker in Victoria,” he says. “He was going to be the number-one mortgage broker in Canada.” Martel came close: in 2009, Canadian Mortgage Professionals magazine named him “best newcomer” to the national scene.
Around 2011, Martel embarked on a house-flipping venture in Victoria. He bought properties, converted them to apartments and sold them at a profit. Maximilian Huxley, a contractor Martel hired in 2011, told me that he asked him to invest in the project, promising extraordinary returns of 15 to 20% per year. But he found Martel’s slick sales pitch off-putting: “that old-school, used-car-salesman approach,” he says. “He would oversell the idea and talk to you about the same thing three different ways.”
Huxley declined to invest. Then, when his work was complete, Martel refused to pay him. Huxley sued to get his money back.
In 2017, Martel registered a new mortgage company: My Mortgage Auction Corporation, also known as Shop Your Own Mortgage. He set up an office in a sleek, blue-glass building with a view of Victoria’s Upper Harbour and refined a new pitch. He told investors they were funding short-term bridge loans, intended to finance specific construction projects. After a few weeks or a few months, the investor would get back their initial investment, plus interest.
“I wanted to leave something to my family, for my kids and grandkids. Something that would be helpful to them after I die.”
Martel’s timing was brilliant. By 2018, Victoria was in the midst of a historic real estate boom. There were nearly 4,300 housing starts that year, more than double the figure of just half a decade prior. Yet this explosion of new construction had done little to dampen prices. The average single family dwelling cost over $900,000 that year, up more than $400,000 over five years. On paper, this made little sense. Victoria is a small city. In 2018, its entire metropolitan area contained only about 395,000 people. It’s also a government town, without the kind of major industry that usually comes with exorbitant housing costs.
But the city is beautiful and temperate, with limited room for expansion. Its population skews older and affluent. And real estate is one of its major industries. In 2018, the year after MMAC was founded, real estate made up nearly 20% of BC’s GDP, a higher share than in any other province. So for those left out of the city’s real estate mania, MMAC seemed just good enough to be true.
Brian MacDonald had watched the property boom engulf his city, leaving him squarely on the sidelines. MacDonald is 55 and works for a tourism business driving a red double-decker bus. He likes his work, but it hasn’t made him a wealthy man. “I’m a thousandaire,” he quips. He’s never been able to save up the kind of money that would buy him even a modest home in the city of his birth. A long-term spinal disability, he says, has sometimes made it especially hard to make ends meet.
Like many Victorians, MacDonald didn’t know if he’d ever be able to own a home in the city, until his former partner introduced him to MMAC. One of MacDonald’s first investments with Martel—about $10,000, a huge sum to him—offered a 17% return over just three months. It yielded the returns promised: $1,700.
MacDonald was ecstatic. He believed he had finally found a way to get a foot-hold on Victoria’s exclusive property ladder. He had deeper motivations as well. “I wanted to leave something to my family, for my kids and grandkids,” he says. “Something that would be helpful to them after I die.”
He upped his investment, giving Martel about $20,000—the entire contents of a registered disability savings fund he held with the BC government. “Any savings that I had, I gave it all to Greg,” he says. He kept at it, reinvesting his MMAC earnings back into the company.
This is how it was designed. After each project was complete, investors got the chance to reinvest in another project. Eventually, many investors had huge amounts of money ping-ponging between MMAC’s fictional projects. This was crucial for the fraud to succeed. It was a classic Ponzi scheme: Martel was paying one victim with the money he received from others, after skimming some off for himself.
MacDonald’s introduction to MMAC, through a family member, was also typical. Martel didn’t promote the company on billboards or in television commercials. Instead, MMAC was advertised in whispers, at family dinner tables and between the best of friends. In some cases, prospective clients were told that there was a waiting period before they could invest. This all gave it a sheen of exclusivity that made it seem more credible. Martel’s victims believed they were getting access to a type of investment usually reserved for the rich and the well-connected.
Judy Collins Hale, a retired HR professional, learned about MMAC from her financial adviser in 2020. “It was like, ‘I don’t tell everybody about this, just my friends,’” she says. This word-of-mouth endorsement from a trusted source compelled her to try it. “It was like a secret society.” Before participating, they had to sign a lengthy form acknowledging, among other things, that the loans they were providing were not a regulated investment vehicle.
Martel’s flamboyant lifestyle helped keep the illusion alive. One MMAC investor described Martel as part of a “hoity-toity, Range Rover and tight pants” set of local realtors and mortgage brokers, whose lifestyle did their advertising for them.
In 2022, Martel bought a seven-bedroom mansion in Las Vegas for US$4.8 million. The same year, he began renting a home in Newport Beach, California for US$37,500 a month. Newport Beach was also the home of CarShair, a car-rental business Martel founded in 2018. And in Victoria, he owned a luxurious 4,200-square-foot hilltop home with a commanding view of the Olympic Mountains across the border in Washington state. He also travelled in luxury. Martel spent about $3.1 million on private flights and accommodation between 2018 and 2023 and about the same amount on vehicle rentals. A former girlfriend told a podcaster in 2024 that he’d flown her on a private jet to Los Angeles, then had a Rolls-Royce chauffeur her into the city. She also claimed Martel flew her to Portugal, Spain and Italy.
That success, or the appearance of it, was intoxicating. In 2022, Martel sent an email to several BC realtors, claiming to know a developer building townhouses in Shawnigan Lake, a resort village north of the city, who was willing to pay high interest rates on a construction loan.
Yet despite catching Martel in an apparent lie, Horsland later invested in a different MMAC project. Too many people were making too much money to pass it up. “If you’re at the casino and you win a lot of money, you don’t want to leave,” he says.
The collapse
If Greg Martel thought he could keep getting away with his scheme, he had good reason to. Canadian authorities are notoriously poor at investigating and punishing financial fraud. That doesn’t mean it’s not happening; the 2026 Global Financial Crime Report, published by Nasdaq Verafin, pegged Canadian fraud losses at $3.4 billion in 2025, an 11% increase from two years prior. That’s faster growth than in any other G7 nation.
The reasons are systemic. Enforcement responsibilities are fragmented between municipal and provincial police forces, as well as the RCMP and regulatory bodies. Police forces, especially smaller ones, often have insufficient expertise in the field. Larger ones are overstretched. In 2023, Parliament’s National Security and Intelligence Committee released a report on federal policing, which said that the RCMP’s expansive responsibilities left it without the capacity to investigate financial crimes adequately. The Mounties, it said, receive far more tips about alleged crimes than they can possibly respond to. And last year, the Ontario Crown Attorneys’ Association said that most fraud cases in the province since 2020 had ended with charges stayed or withdrawn, in part because cases were too complex for the province’s overburdened criminal justice system.
Even when crimes are rooted out, they’re rarely penalized substantively. Earl Jones, the Montreal Ponzi scammer who defrauded dozens of elderly investors out of tens of millions of dollars between 1982 and 1999, served just four years of an 11-year jail sentence. In 2024, TD Bank pleaded guilty to money laundering after criminal networks spent years filtering drug-trafficking profits through the bank. Courts found that the bank failed to monitor suspicious activity — and, in some cases, employees knowingly assisted criminals. In the United States, the bank received US$3 billion worth of fines. In Canada it was hit with a $9.2-million penalty. That was a record at the time.
Banks are required by law to flag suspicious activity, and there was no shortage of it. Martel was a regular at an RBC branch near his home in Victoria and made thousands of transactions with the bank—all of which were later determined to be fraudulent. But if RBC ever looked twice at Martel’s accounts, it never stopped servicing his company. Perhaps more damningly, the BCFSA received reports about Martel in 2017 and its investigations turned up nothing. The authority also referred those complaints to the province’s securities commission, but nothing came of that either.
In this lax environment, MMAC might have continued for years longer. What it could not avoid was the inevitable death spiral that befalls all Ponzi schemes. These cons operate on the logic of constant growth, with larger infusions of money needed to pay off the growing number of investors. As soon as growth stalls, the operation enters its terminal phase. Every Ponzi scheme eventually meets this fate, including the one that gave them their name: in 1920, a Bostonian named Charles Ponzi set up a fraudulent investment corporation, which he only kept going for a year before it collapsed. In this century, American financier Bernie Madoff ran an investment firm that defrauded thousands of people of $65 billion—the largest Ponzi scheme ever perpetrated. It too fell apart.
By 2022, Martel was riding high on MMAC’s success, but the inflow of new investors had slowed. In a bigger city, Martel might have kept MMAC going longer, but in and around Victoria, the pool of potential victims was shallow. And so he changed tack, supplementing his whisper network with active solicitation. Some investors received texts and emails from Martel offering private offers at double the usual interest rate.
One client, a woman in her early forties named Bree Woods, noticed when he began splitting investment opportunities into two shorter periods, encouraging more people to put money in faster. That made her nervous. MMAC had been a cornerstone of her financial life since 2019, when she got a tip from her sister’s financial adviser and started investing with Martel. She ended up putting about $525,000 into the company. She planned to use it to buy a condo in Vancouver for her daughter and, ironically, to diversify her own investments.
She decided to withdraw some of her money. She’d done so before and had no problem—but this time, it never came. Martel said that MMAC was reconciling paperwork and asked for patience, but Woods began peppering him with emails and calls. She threatened to sue to get her money back, but she held off. “He always had a story,” he says. And MMAC had been good to her. This was the first time in her life she’d had a lot of money.
“Greg wanted this to be abundantly clear, so here it is again... GREG IS PAYING EVERYONE BACK.”
Other investors were also getting frustrated. Soon, Martel was hosting Zoom calls to update them, making excuses for the late payments. He blamed tax issues, staffing problems in his office and, sometimes, them. “This is not your life savings that should be in here,” he said in one online meeting in February of 2023.
Like Woods, Laurel Rayani was a long-time MMAC investor. She did not respond to requests to speak with me for this story but, according to an affidavit filed in British Columbia’s Supreme Court, she was approached in 2018 by mutual acquaintances of hers and Martel’s, who told her about MMAC. She needed financing for a charity she ran to support marginalized adults and young children. Over several years, she invested hundreds of thousands into MMAC and used the interest from those investments to pay her bills and support her organization. Martel twice donated large sums directly to the charity.
In 2021, Rayani told Martel she wanted to withdraw her entire investment—about half a million dollars—to buy a rural property for the charity. Martel instead offered to broker a mortgage, and MMAC helped Rayani secure a line of credit worth more than $1.4 million. Her money stayed in MMAC.
But by late 2022, Rayani was running out of cash, so she tried again to withdraw funds. Martel delayed and, in February of 2023, Rayani’s charity ceased operations because of a lack of financing. That month, her lawyer sent a letter to Martel demanding her principal and interest, plus reimbursement for legal fees—more than $2.4 million altogether. Weeks later, Martel’s lawyer wired her lawyer the entire amount.
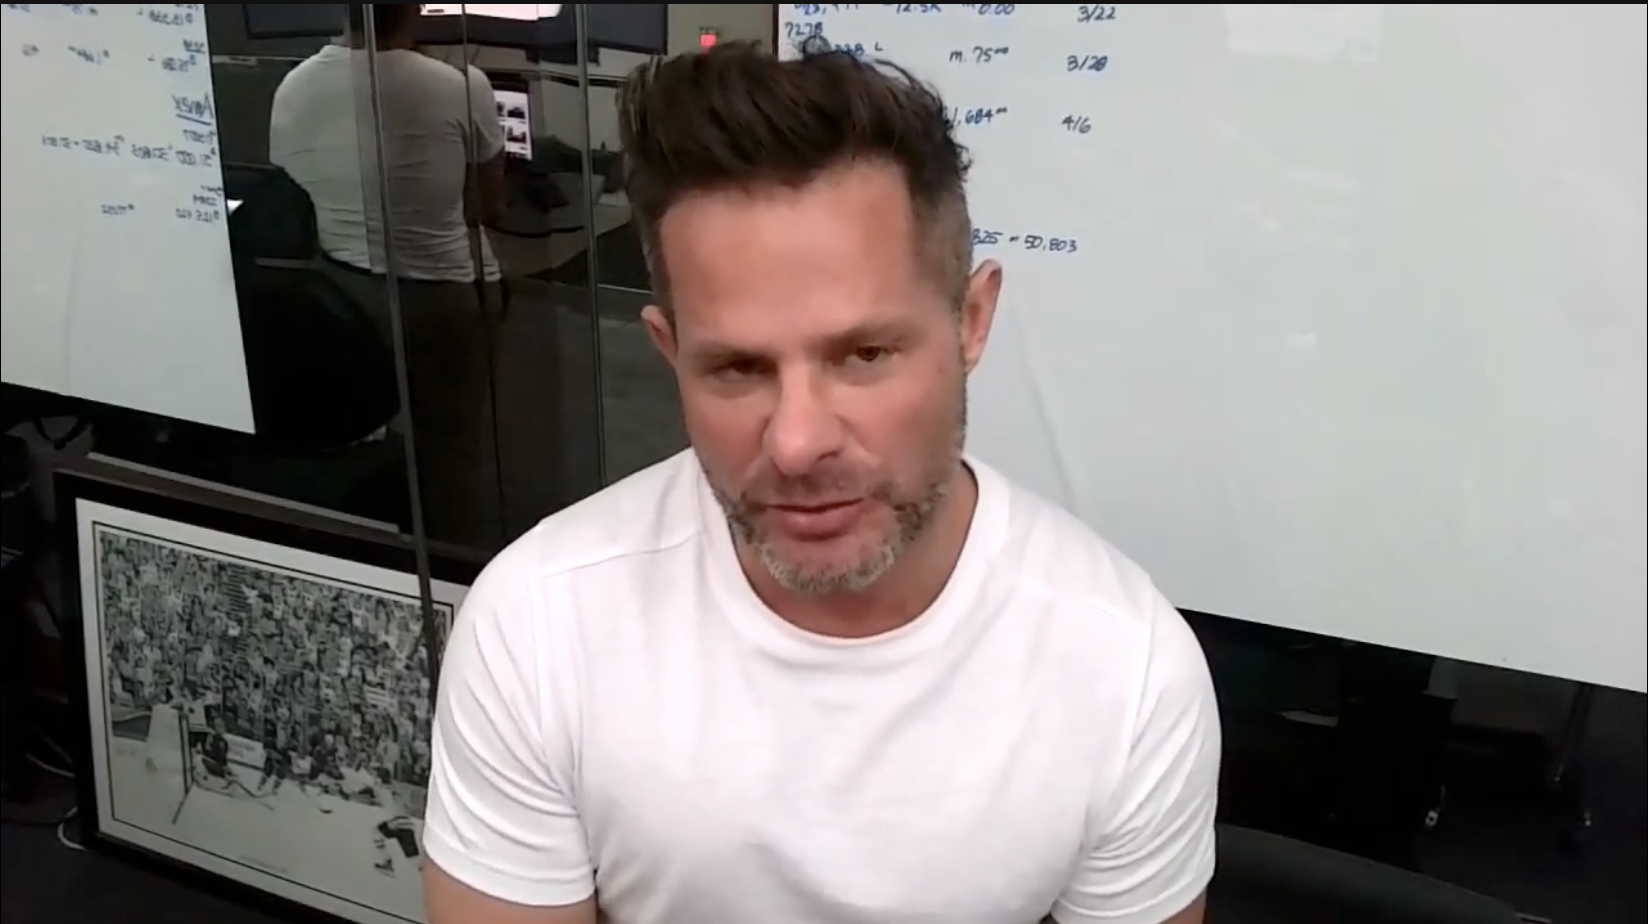
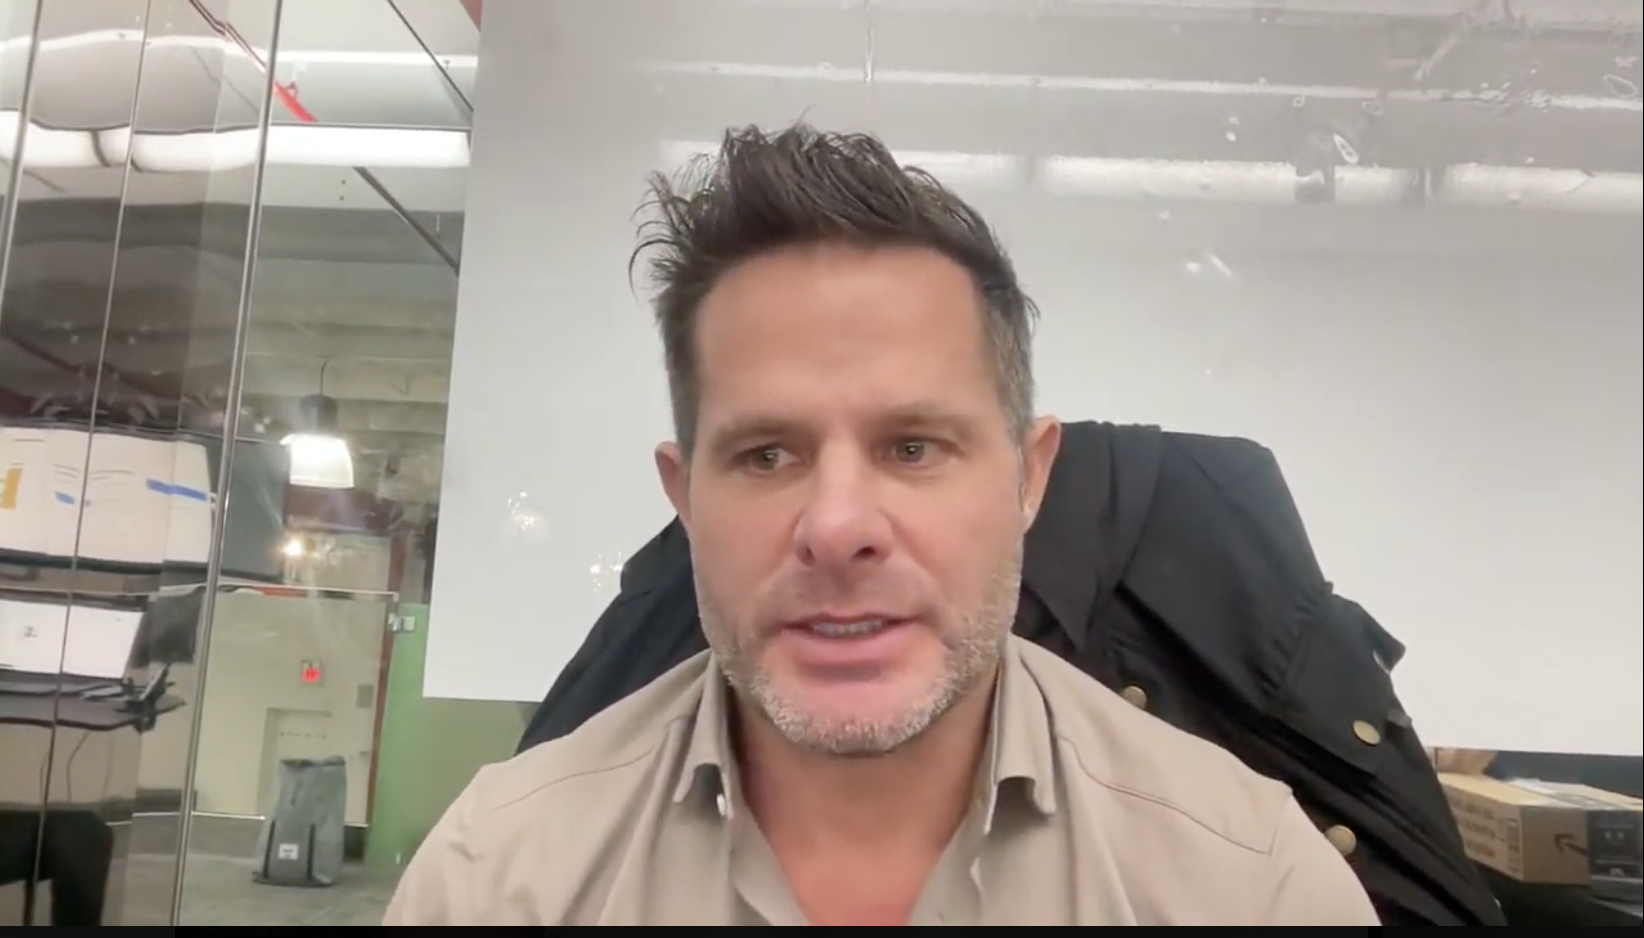
As Martel's scheme began to collapse, he began hosting routine video calls like the one pictured here where he told investors their money was coming. (Screen capture)
But Martel’s troubles didn’t end there. The BCFSA received new complaints from five separate investors. One had visited MMAC’s Victoria office and found it empty. Others explicitly suggested the company might be a Ponzi scheme. Yet still MMAC was emailing investors about new opportunities. In a video call in April, a haggard-looking Martel told them that the worst was over. “We are past the major part of our backlog,” he said. “Honestly, it’s just downhill from here. I really hope that relieves a lot of people’s anxiety.”
Two weeks later, Martel’s executive assistant wrote to investors, saying Martel was in Thailand and had been delayed by food poisoning.
“Greg wanted this to be abundantly clear,” she wrote, “so here it is again... GREG IS PAYING EVERYONE BACK.”
Finding Martel
In May of 2023, several of Martel's investors crowded into a Vancouver courtroom, hoping to finally confront him. A numbered company in Alberta claimed it was owed roughly $17.6 million for investments into MMAC and had filed suit against Martel in BC’s Supreme Court. The defendant never showed up. But, faced with a slew of complaints about unpaid debts, the court put MMAC into receivership and appointed accounting firm PriceWaterhouseCoopers to settle its accounts.
In August, Martel claimed through a court filing that he had committed no crime. The next month, his lawyers resigned, citing “ethical reasons.” Throughout, PwC said Martel refused to answer questions or respond to court orders. PwC’s autopsy of MMAC confirmed that the business was entirely fraudulent: out of more than 65,000 transactions connected to it, not a single one involved a real loan to a developer.
In Martel’s absence, a legend grew around him. Some victims assumed he was sitting on a beach, sipping cocktails bought with their stolen money. One person told me he would never be found because he was probably wearing a new face, stitched on by some unscrupulous plastic surgeon. Barron and Nancy Harper heard he’d been murdered.
One of MMAC’s investors had the drive, spare time and financial resources to go after Martel himself. Daniel Castellini is a California entrepreneur who met Martel there. Their acquaintance led to Castellini and a group of creditors investing about US$2 million into MMAC. Once Martel disappeared, Castellini hired private detectives in the US and Thailand, who scoured phone records, knocked on doors and even visited gyms around Bangkok. Eventually they narrowed in on a resort near Phuket and reported Martel to Thai authorities for overstaying his visa.
Castellini flew to Thailand and found his quarry in prison. He says that Martel signed over the equity in his Las Vegas home to him and confessed to his crimes, but did not seem remorseful. The main thing Castellini remembers is that Martel couldn’t stop complaining about the ants that crawled over him at night. “It was all about himself and these ants,” he says.
Ultimately, Castellini’s vigilante approach didn’t pay off. Martel’s assets had been frozen, and PwC went to court to get the Vegas property back. Still, in Castellini’s mind, he’d gotten some measure of accountability that the justice system had failed to deliver.
Martel was deported from Thailand in late August of 2023. According to court records, his next stop was Dubai, a city with a reputation as a haven for white-collar criminals on the run. Once again, Greg Martel was in the wind. His victims believed he had probably taken a new name and found a comfortable place to hide with the rest of his stolen money.
“There’s been this stuff online that distorts what I’m saying, or makes things look worse than they are.
This past June, it was revealed that Martel had been arrested in the eastern European country of Georgia. Officials have said little about the circumstances of his arrest. I was able to contact Martel’s lawyer in Georgia, as well as a Georgian journalist, who told me that Martel had been arrested on drug-trafficking charges in Batumi, near the Turkish border. Foreigners have faced drug charges in Georgia for innocuous offences such as carrying Adderall without a translated prescription. Martel’s lawyer didn’t respond to questions about why he was arrested. Martel took a plea deal in February of 2025, agreeing to a 12-year prison sentence, and is now in Geguti prison in western Georgia, a facility known for failing infrastructure and a culture of violence.
In some ways, Martel’s current circumstances are worse than anything a Canadian court could dish out. If charged with fraud and convicted here, Martel would face a maximum sentence of 14 years, presumably in a relatively more comfortable Canadian institution. But this may never happen, since Georgia has no extradition agreement with Canada. One hot day this summer, I was taking shade in the shadow of a cathedral in downtown Vancouver when one of Martel’s investors called me. I told her what I’d learned about his sordid condition. She was delighted. “I hope the rats gnaw on him,” she said.
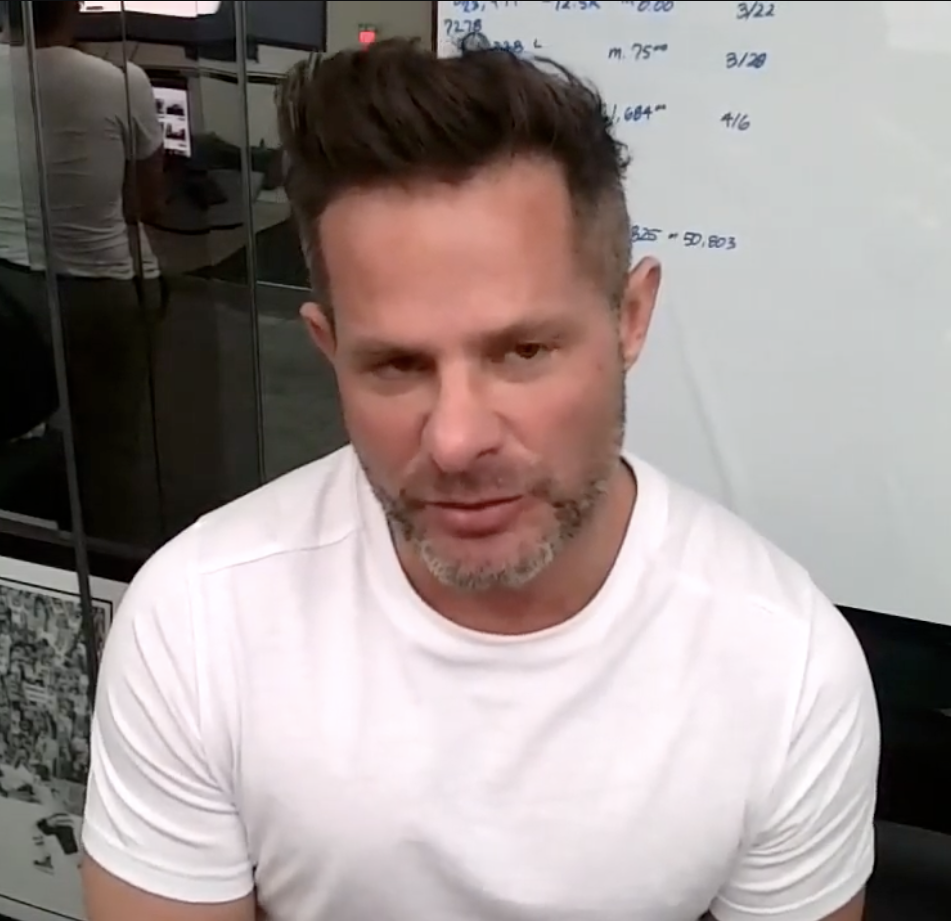
For weeks, I called Martel's lawyer to ask if I could speak with his client. I also phoned the prison where Martel was held, leading to a nonsensical conversation with a bemused Georgian prison guard. I assumed I wouldn’t succeed. And then, one day, Martel called. The connection was staticky and muffled, but it was unmistakably him—and now it was my turn to be solicited by Greg Martel.
He said several journalists had contacted him, some offering money. The implication was clear: even behind bars, he was trying to cut a deal.
I told him that I had spoken to more than a dozen people who said he had defrauded them. I asked if it was true that he had run a Ponzi scheme. He didn’t answer directly, but said, “There’s been this stuff online that distorts what I’m saying, or makes things look worse than they are.” He also said he had to be careful what he said, “because of my case in Canada,” implying he may seek extradition.
That was all. He told me he was weighing various offers for interviews and would decide later who to speak to. “What I’ll do is, if I decide tonight, I’ll call you back.” I never heard from him again.
The fallout from MMAC was immense. Bree Woods moved into her own basement so she could rent out the rest of her home to cover expenses. The debt and stress of the ordeal weighs heavily on her; she’s developed ulcers and wakes in the night with splitting headaches.
“I’m not going to let Greg Martel kill me."
Woods is one of about 480 victims whom PwC has declared “net winners” of Martel’s fraud, in that they received more money from the scheme than they put in. In 2025, the BC Supreme Court approved a proposal by PwC requiring those investors to pay back their profits to be redistributed to the “net losers.” In February of 2025, the company estimated the value of those clawbacks could be as high as $71 million.
Most of the supposed winners, of course, never imagined needing to pay back their investments. In many cases, they no longer have the money to do so. Some also question PwC’s math. Woods has been asked to pay back $18,900, but by her accounting, she lost about $200,000. She’s fighting the decision in court. PwC recently seemed to acknowledge that some of its original calculations were wrong; this August, the firm announced that more than 400 parties had disputed its clawback claims and said it now expects to recoup just $36 million.
As of last December, the receiver had collected more than $9 million from the sale of Martel’s properties in Victoria, Las Vegas, and Ontario. But most of that money appears to have been paid to major creditors, especially RBC. The net losers say they have yet to receive any payments, and many worry they never will. PwC has estimated it will bill more than $12.2 million in fees to complete its work as receiver. Rick Horsland—the Nanaimo realtor who uncovered Martel’s early ruse, only to invest later—worries money intended for victims may end up going to accountants and lawyers instead.
After the BC Supreme Court declared MMAC to be a Ponzi scheme, victims assumed the CRA would forgive the taxes on their MMAC windfalls. Instead, many victims, even those who lost money, say the CRA continues to knock on their doors. They claim the agency has been garnishing wages and even threatening to put liens on homes, which it has legal authority to do. I reached out to the CRA, but it refused my interview request. The takeaway is stark: institutions were inept when it came to catching Greg Martel, but brutally effective when it came to squeezing more money out of ordinary people.
Andrew Wilson, an engineer who lost his entire $100,000 investment in MMAC, believes the CRA and the BC Securities Commission should have spotted Martel’s crimes. “There are checks and balances in our society that should have picked up on this,” he says.
In the spring of 2025, Wilson became one of three representative plaintiffs in a proposed class-action lawsuit against RBC, arguing that the bank failed to detect red flags. (RBC declined to comment for this story and, as of this writing, has yet to file a response to the allegations.)
Some of Martel's victims argue RBC, his bank, ought to have flagged the tens of thousands of transactions in his accounts. Photo: Shutterstock
The lawsuit was also originally named the BCFSA, which is entrusted with regulating mortgage brokers like Martel. But in August, the authority reached a deal with the plaintiffs in which it agreed to hand over details about the complaints filed about Martel, as well as communications between the authority and Victoria Police. The plaintiffs hope this will be useful in their suit against RBC.
The BCFSA says a new BC law, to take effect this month, will expand its investigative powers and allow it to charge mortgage companies as much as $500,000 per contravention for wrongdoing. And this spring, the federal Liberals proposed setting up a new agency, distinct from the RCMP, to be tasked with investigating financial crimes. This might herald a new era in the fight against fraud, but details are thin so far. Some experts, while welcoming the announcement, have noted that it seems to be an indictment of the RCMP’s ability to handle these cases.
For Martel’s victims, any such reforms come too late. Brian MacDonald, the tour-bus driver who had hoped to finally buy a property of his own, lost his entire life savings. Judy Hale and her husband, David, used their interest revenue from MMAC to buy a motor home and travel the country on camping trips. The company was declared bankrupt on David Hale’s 67th birthday and, after that, he started driving for Uber; he later returned to his work as a realtor, with Judy as his assistant. “I’m not going to let Greg Martel kill me,” she says.
For Nancy and Barron Harper, MMAC’s collapse put an end to the life they had waited so long to build in Victoria. They were forced to sell their home and move in with another of their sons and his family in Austin, Texas. The combination of legal fees and clawbacks has gobbled up whatever savings they had. I last spoke to Barron in May of 2026, a month before his 80th birthday. Instead of preparing celebrations, he was staring at a laptop in his son’s basement, trying to revive his tax accountancy. He and Nancy were running out of money, and he needed to go back to work.
Greg Martel’s victims thought they were getting rich off Canada’s housing boom. Instead they lost everything. Will the notorious Ponzi schemer ever face justice?
Local food truck business targeted by vandals this summer
All three of Greek n' Go's food trucks have been damaged or broken into this summer.
BC Supreme Court upholds first-ever jail sentence for man who killed 2 black bears in his Tofino backyard
The man shot a nursing mother bear with four arrows and its young cub while they were 15 feet up a tree.
The best morning read in Victoria, bar none.
Stay connected to your city with the Capital Daily newsletter.
By filling out the form above, you agree to receive emails from Capital Daily. You can unsubscribe at any time.